

Self-Managed Super Fund Finance Solutions
Commercial SMSF lending for today's market
New SMSF borrowing for property now centres on business-use assets, so commercial property has become the primary path for building wealth through your super fund. We structure the loan to ensure your asset is correctly held within a Bare Trust, so you can capture capital appreciation while supporting your fund's compliance requirements.
To make it work, we translate your fund's balance into genuine purchasing power, accessing specialist lenders who fund commercial acquisitions within your SMSF.
Backed by Australia’s leading specialist lenders for complex entities and self-managed super funds
Integrated lending structures for self-managed investors
Commercial Premises
Secure your business headquarters via your SMSF. We arrange facilities where business rent pays down the loan, building equity within your fund over time.
Commercial Investment
Diversify your fund with income-producing commercial assets. We access lenders for retail, industrial, and office properties across Queensland's commercial corridors.
SMSF Refinancing
Refinance legacy debt to improve fund cash flow. We transition existing facilities to competitive market rates, reducing interest costs to accelerate your net asset value.
Compliance & Strategy
We work with your accountant and planner to ensure Bare Trust and loan structures meet strict ATO guidelines, supporting your fund's ongoing compliance.
Frictionless coordination with your advisory team
Delays in SMSF settlements typically stem from incomplete entity setups or lags in rolling over funds, compounded by the complexity of processing trust structures through standard banking channels.
Engaging your advisers early is critical. Once established, we act as the central conduit between your accountant, planner, and the lender, managing the technical execution for a compliant settlement.
Aligning retirement capital with infrastructure growth.
From the Olympic precincts to major transport upgrades, we identify commercial assets positioned to benefit from South East Queensland's infrastructure pipeline.
We present these drivers to lenders to mitigate their risk concerns, helping you secure funding for high-demand locations with long-term capital upside.
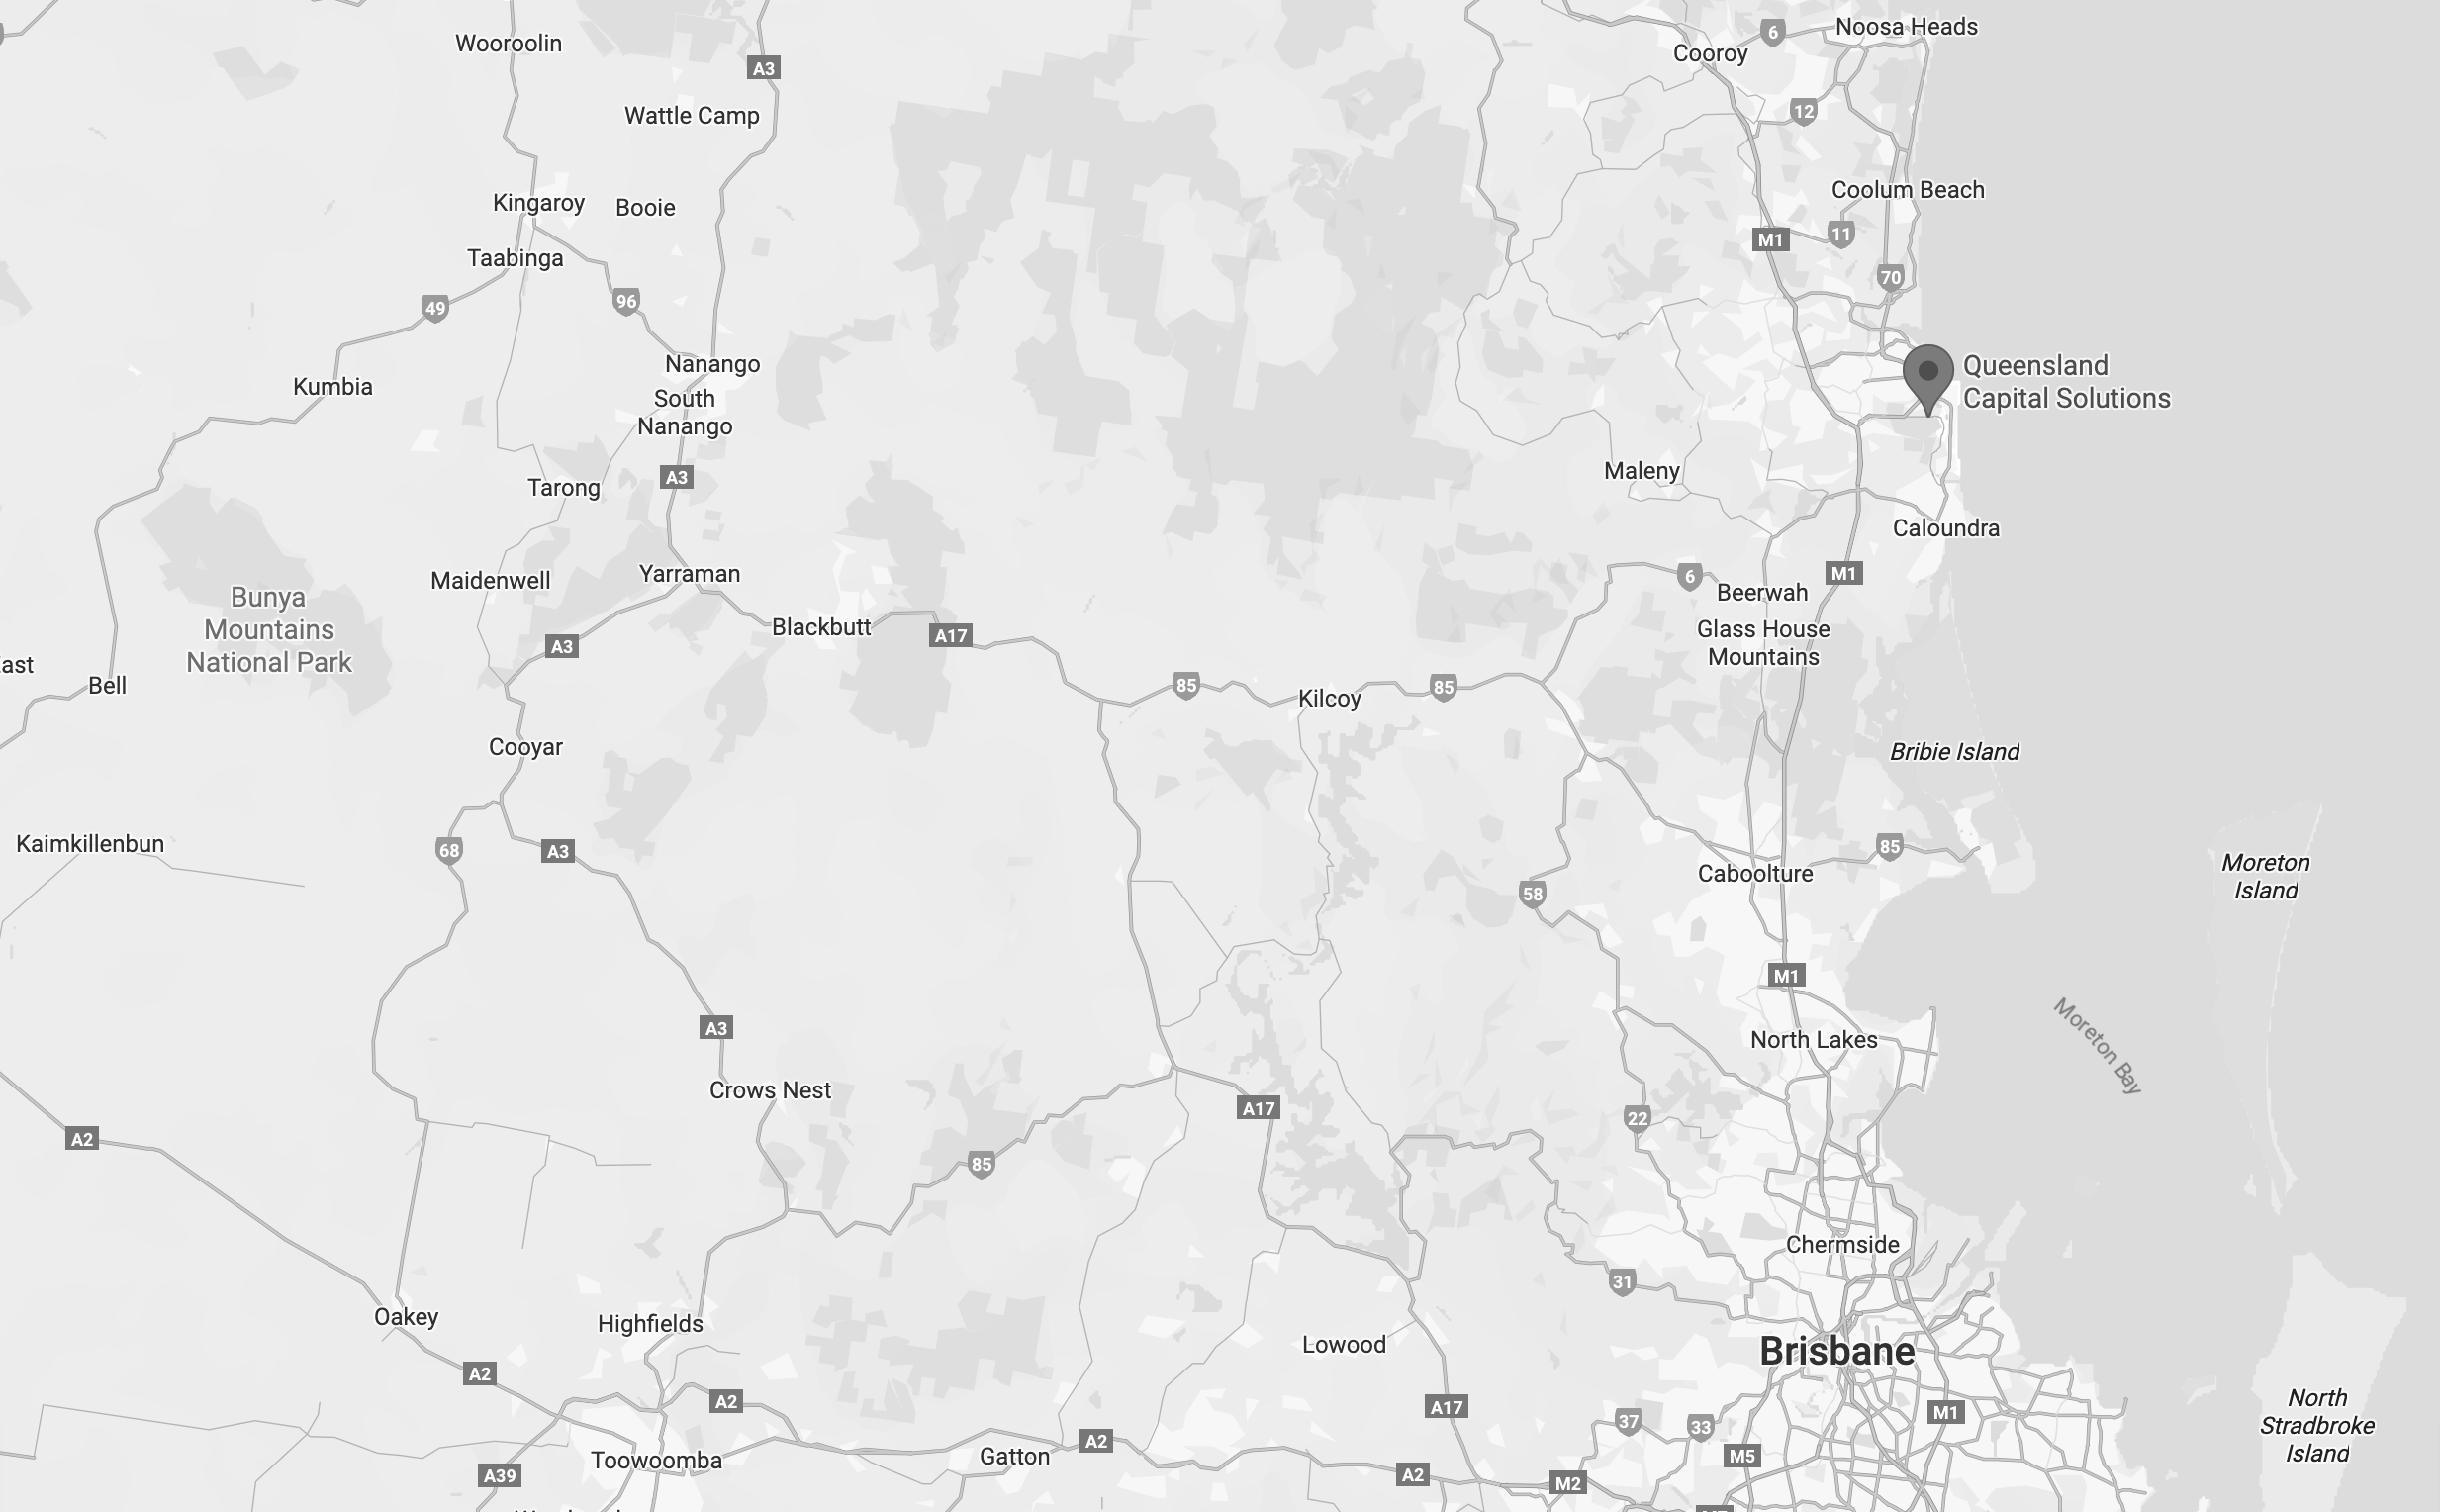
Core Markets: Sunshine Coast • Brisbane • Gold Coast • Regional QLD
Case study
A multi-layered SMSF acquisition for an experienced investor
Challenge:
An experienced investor wanted to buy a Victorian property through their SMSF to build retirement wealth. However, a recent job change, irregular super contributions, and a past credit issue made standard lenders hesitant to proceed.
Strategy:
Working closely with their financial planner, we modelled borrowing capacity and ensured the SMSF was set up correctly. We then used our direct lender relationships to address the credit issue upfront, proving the strength and stability of their new employment.
Outcome:
By anticipating the lender’s concerns and presenting a clear case, we secured the funding approval to meet strict settlement deadlines. The client successfully purchased the property, overcoming early hurdles to take a major step forward in their retirement strategy.
SMSF Finance
Common Questions
-
Yes. New SMSF borrowing is now generally limited to business real property, meaning property used to run a business, such as your own premises or a commercial building leased to a business tenant. What matters is how the property is used, not how it is zoned. For many investors commercial is now the more strategic play, often with stronger yields and longer lease terms, and where you own your premises the rent grows your retirement wealth instead of paying down a landlord's mortgage.
-
Since the major banks withdrew from the sector, SMSF lending is now the domain of specialised Tier 2 banks and private funders. With new borrowing focused on business real property, these lenders have concentrated on commercial, and finding the right one for your fund takes genuine market knowledge. We hold direct accreditations with these niche lenders, giving you access to competitive rates and interest-only terms that are no longer available on the high street.
-
Yes. Acquiring "Business Real Property" can be a smart strategy for directors. Your trading company pays rent directly to your SMSF, with the fund's concessional tax treatment potentially enhancing your retirement wealth. Your accountant can confirm how this applies to your specific structure.
-
The biggest error is signing a purchase contract before your entity structure and funding strategy are fully aligned. An incorrectly executed contract can cause major compliance headaches or invalidate the loan. We coordinate closely with your accountant to ensure your structure is purchase-ready before you make an offer.
-
Due to the regulated nature of the product, lenders generally require a larger deposit than residential loans — typically 10% to 30% (70–90% LVR). However, we can source lenders that allow you to bring forward future super contributions, giving you the flexibility to boost your deposit and overall borrowing capacity.